The outlook for cash
What you need to know
-
Interest rates are expected to fall after rising in recent years
-
Stocks are more volatile but offer the best opportunity for inflation-beating returns
-
The power of compounding can have a dramatic effect in the long term
-
Consider how you transition from cash to stocks
As interest rates rose in 2022 and 2023, cash quickly became an attractive option for investors following years of near-zero returns.
However, with central banks signalling that interest rates in the US and Europe will gradually fall during 2024, this picture has changed once again – cash returns are set to become less competitive over the coming years.
Better alternatives to cash?
Following the Global Financial Crisis, central banks in many major economies cut their interest rates close to zero (and into negative territory in some places). That was broadly the status quo for more than a decade until soaring inflation became an issue for policymakers.
As interest rates rose, cash understandably became a much more enticing prospect, but that situation is now changing. From this starting point, cash returns may still beat inflation over the long term, but there may be better value elsewhere. One obvious candidate is the stock market.
We know that there are often reasons to shy away from stocks. Returns can be volatile over the short term, particularly at times of economic uncertainty. Factors such as interest rates, market sentiment and subjective expectations can all contribute to fluctuating valuations, causing stock prices to diverge from profits and prospective growth – in either direction.
Over the long term, however, stocks offer the best inflation-beating returns. Corporate profitability – which is underpinned by the upward trend in economic growth – is the main driver of long-term returns.
Cash may or may not beat inflation over a given time period, but even if it does there's an opportunity cost of not owning stocks in the long term.
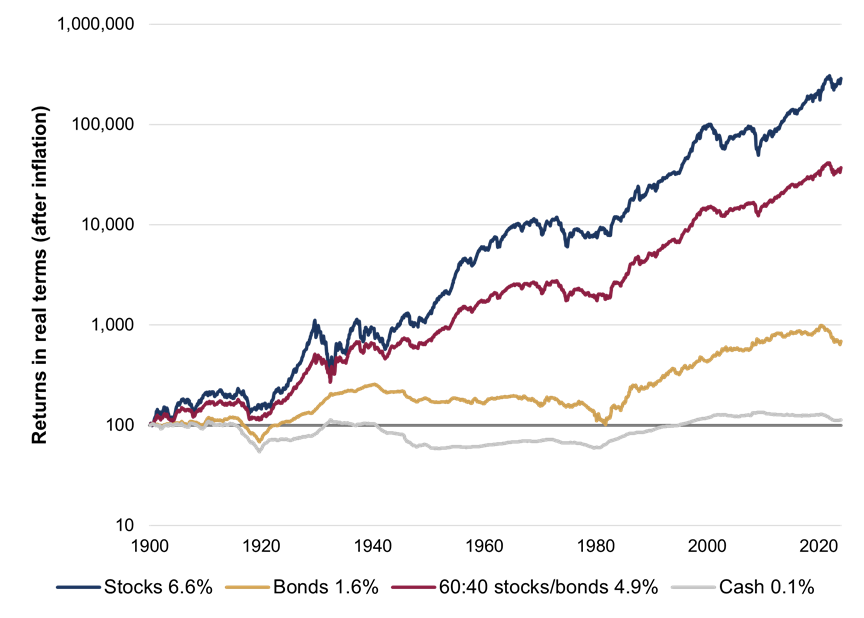
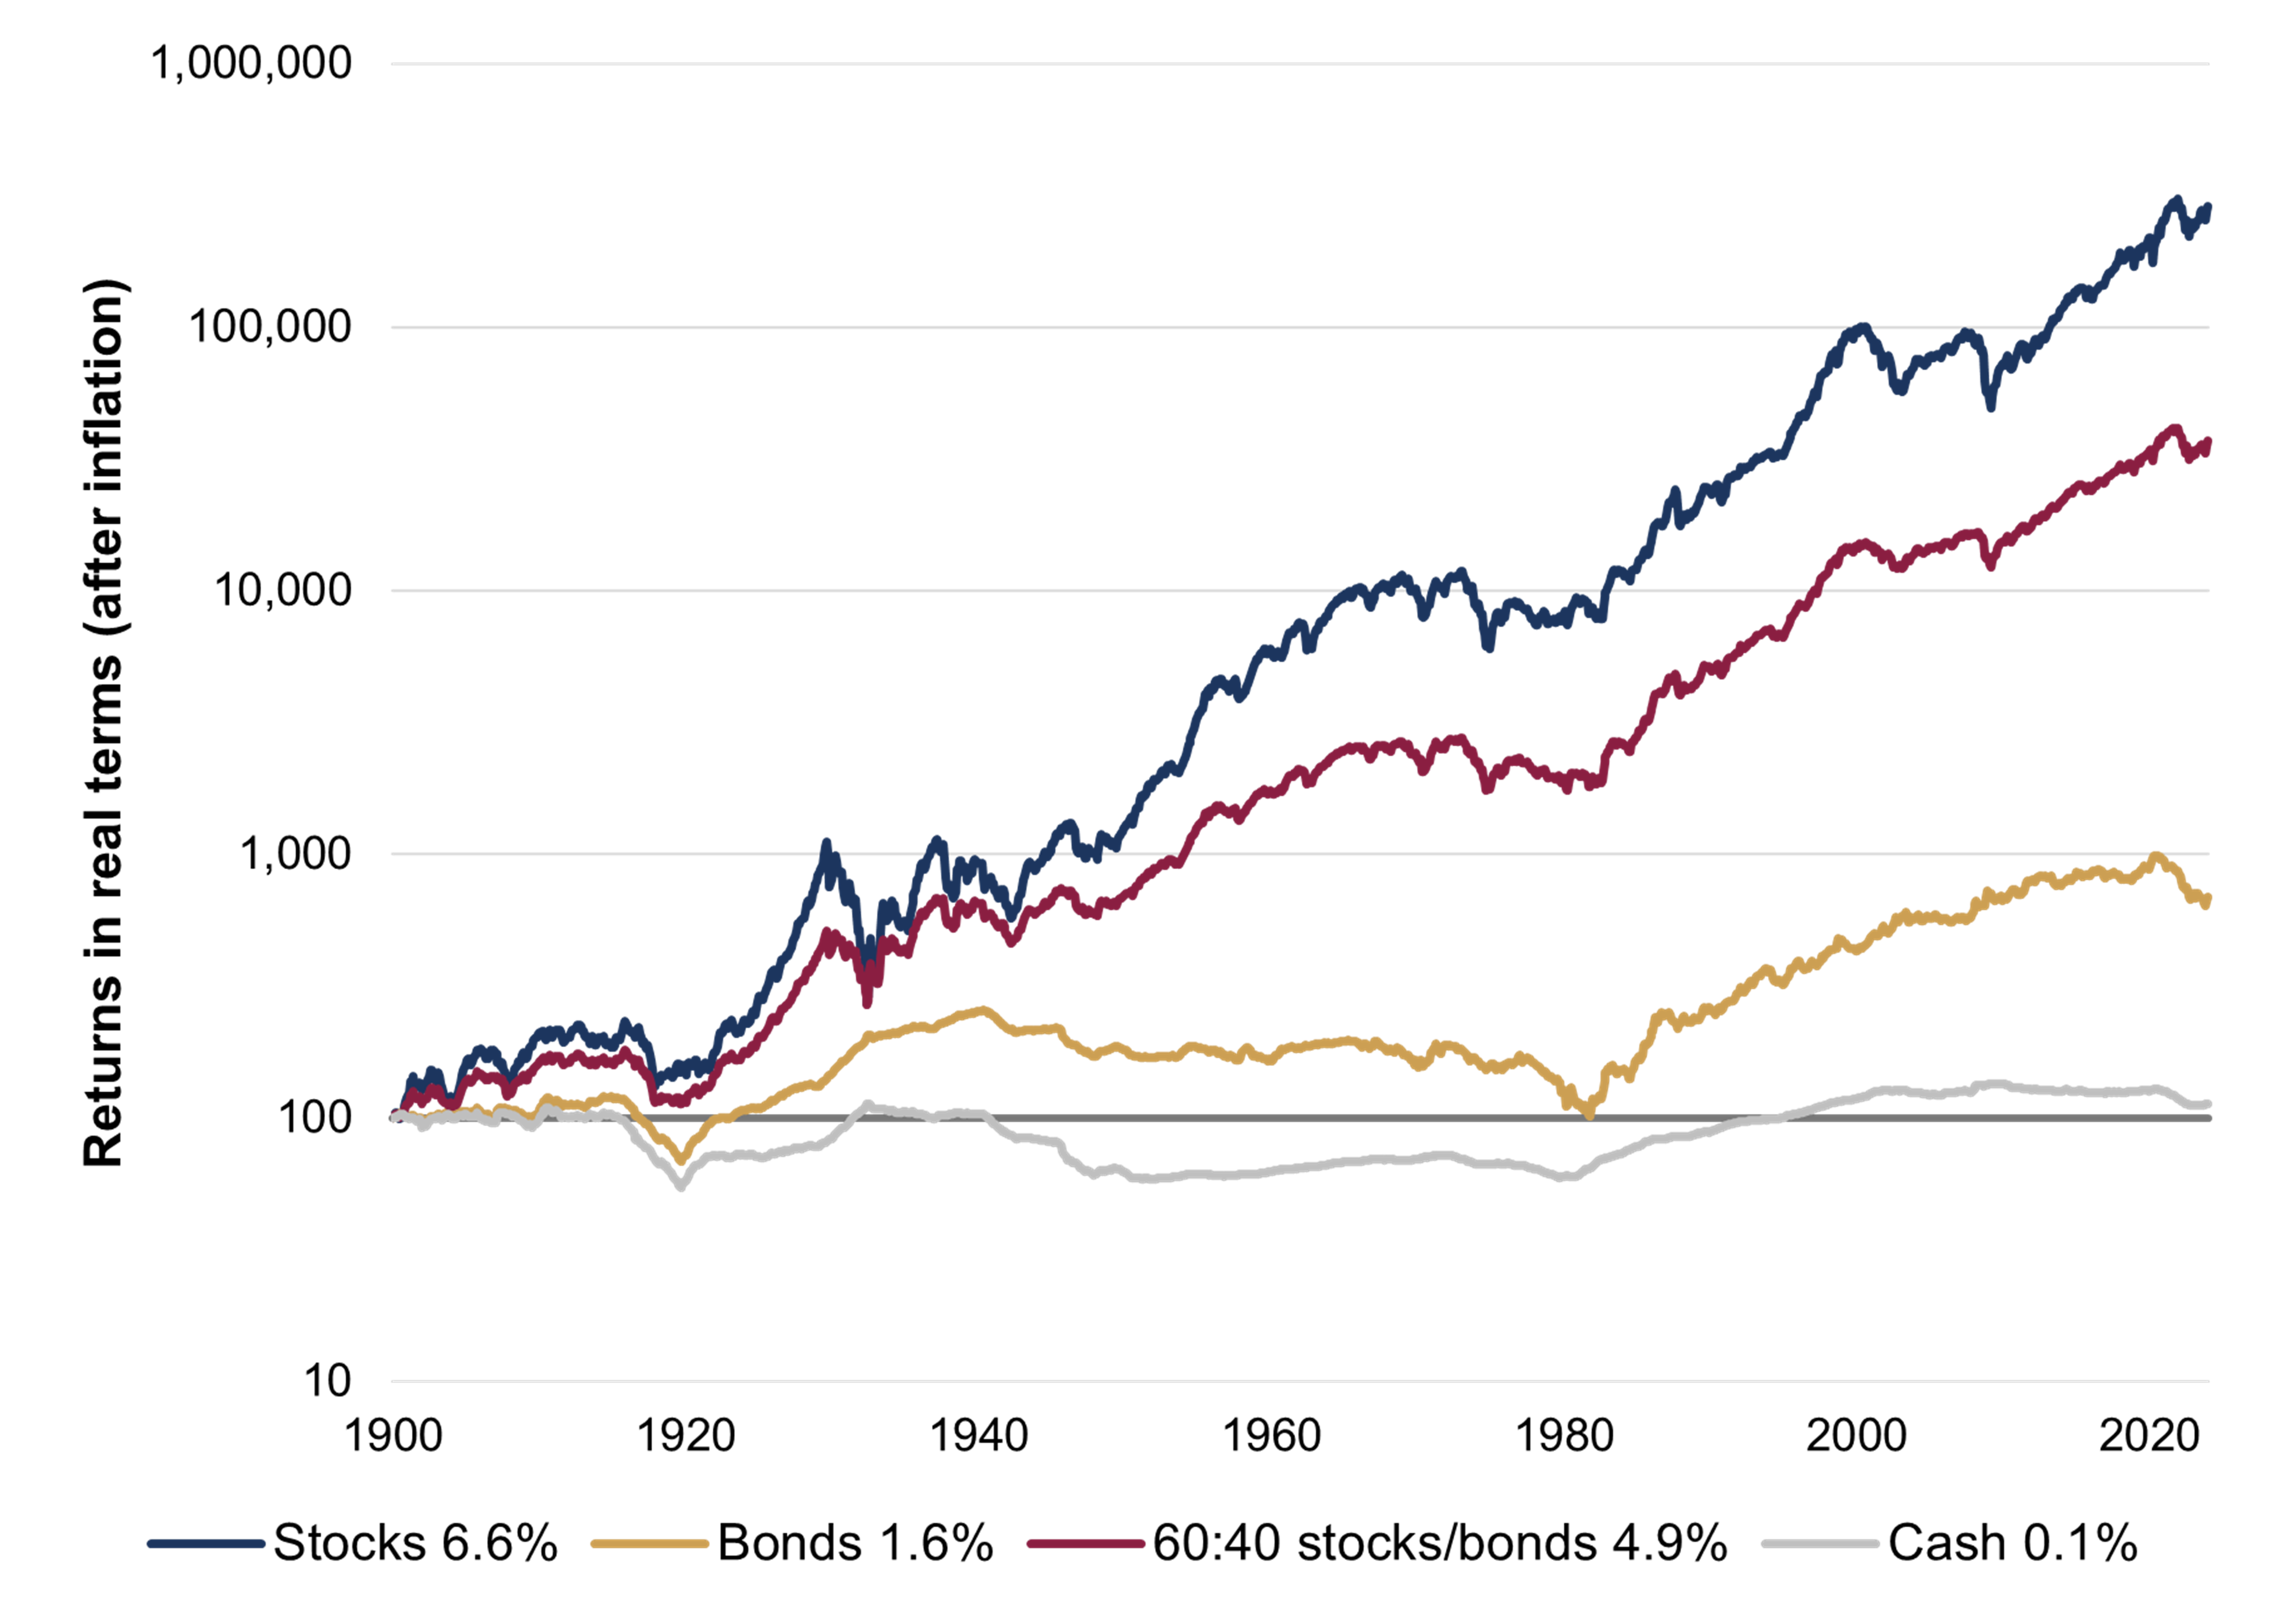
An investor in the stock market is essentially in the van of long-term economic growth and stands to benefit from their ownership of innovative products and services. This trend is clear in recent decades, and over much longer periods. US stocks have comfortably beaten cash returns since 1900 – despite US interest rates averaging 3% during this period.1
Investor returns in real terms (after inflation)
Source: Rothschild & Co, Bloomberg
Source: Rothschild & Co, Bloomberg
The power of compounding
Stocks have partly delivered these strong returns due to the power of compounding over the long term.
Even a modest difference in return can add up to a significant sum once viewed over a period of many years. We can use reasonable expectations of asset class returns over the next decade, to illustrate this.
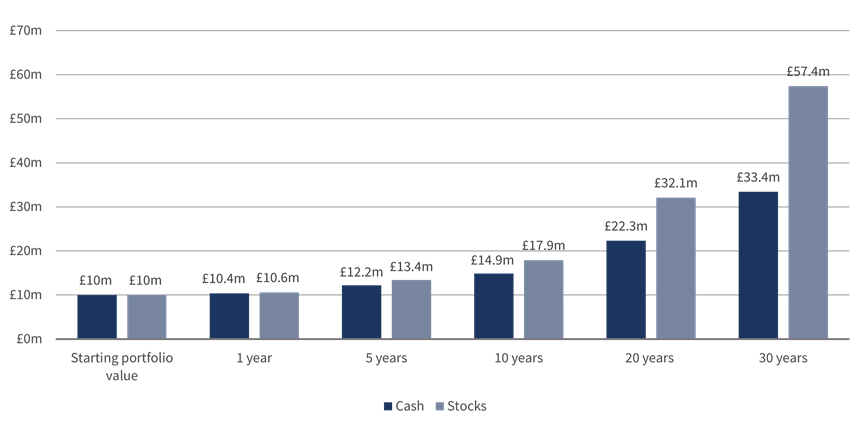
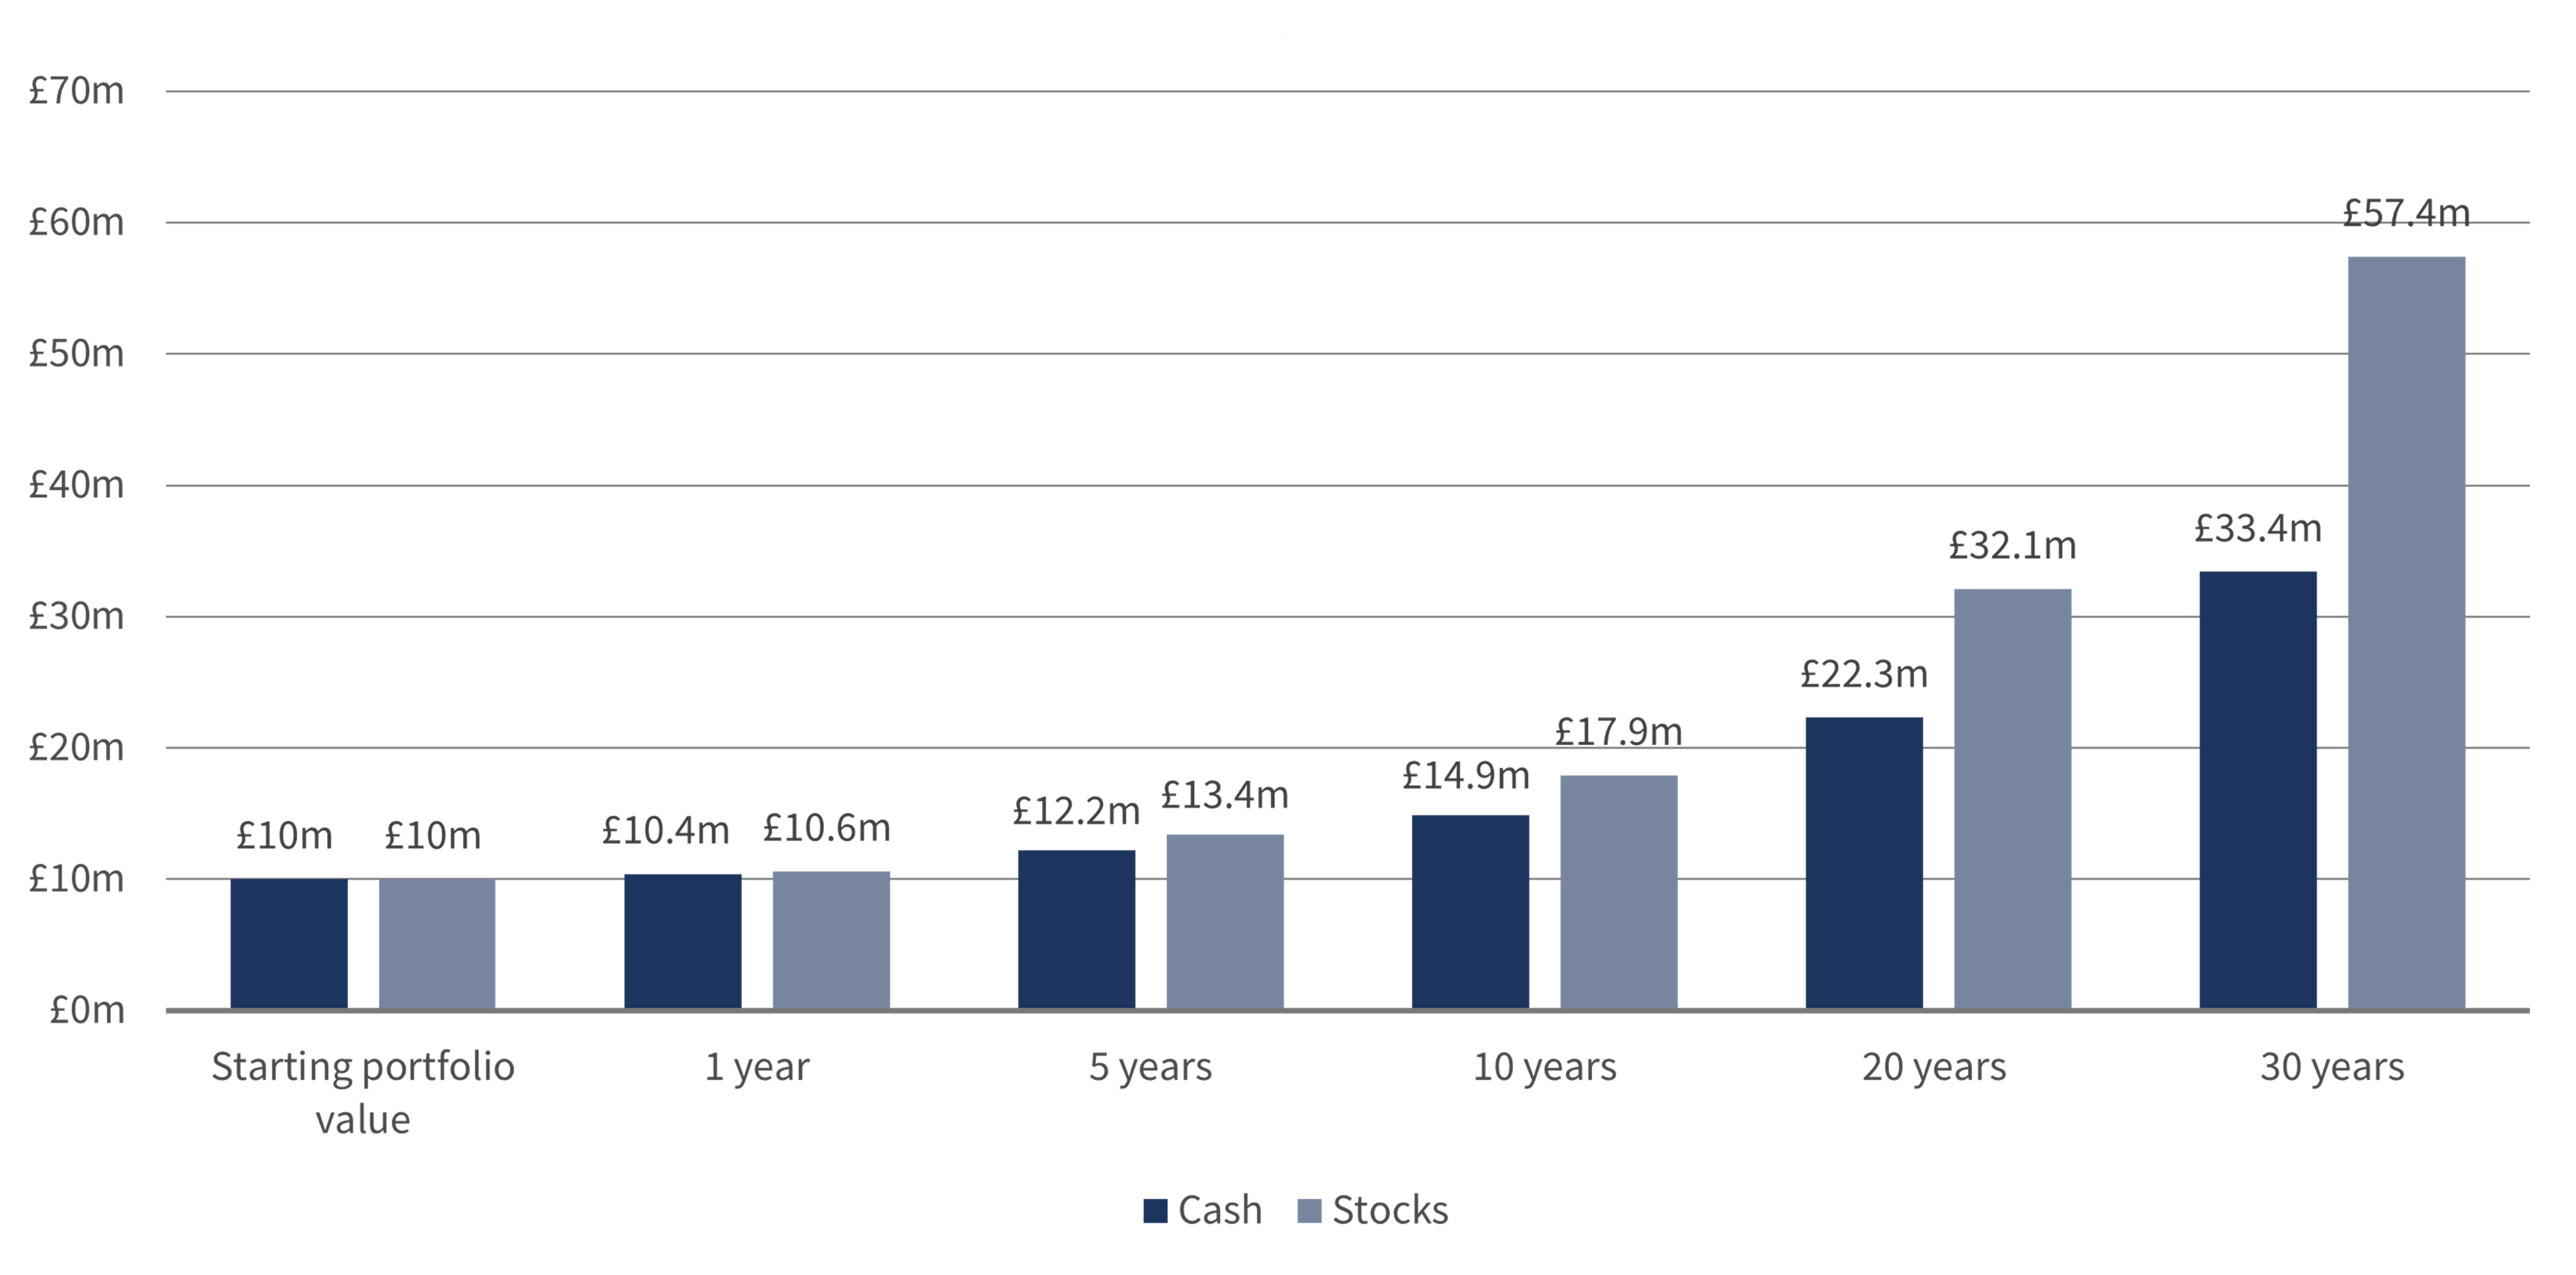
If we assume cash returns 4.1% (annualised) while global stocks return 6%, then an investor with a starting pot of £10 million would have grown their investment portfolio to £17.9 million after 10 years, versus £14.9 million for cash (gross of fees or transaction costs).
However, over longer periods this difference becomes more apparent. By 20 years the cash portfolio would have grown to £22.3 million, less than the £32.1 million return for stocks, while after 30 years the two portfolios would be valued at £33.4 million and £57.4 million respectively.
Source: Rothschild & Co, Bloomberg
Forecasts are not a reliable indicator of future performance. Data correct as of 31 December 2023. Forward return estimates are ‘reasonable expectations’ over a rolling 10-year period, driven by both valuations and a few objective inputs. It is important to recognise that individual years will likely diverge significantly and the range of returns over shorter periods is far wider.
Source: Rothschild & Co, Bloomberg
Forecasts are not a reliable indicator of future performance. Data correct as of 31 December 2023. Forward return estimates are ‘reasonable expectations’ over a rolling 10-year period, driven by both valuations and a few objective inputs. It is important to recognise that individual years will likely diverge significantly and the range of returns over shorter periods is far wider.
Finding a place for cash
Preserving wealth in ‘real’ terms is the cornerstone of our investment philosophy and stocks are the asset class most likely to clear the inflation hurdle over the long-term.
Investors should consider having some exposure to stocks, either as part of a multi-asset portfolio or as a standalone investment.
With that in mind, it’s worth considering how to phase into an investment portfolio. You don’t have to commit all your wealth to an investment portfolio on one day.
It’s common to split up a cash lump sum into several smaller amounts and invest these at regular intervals over a period of time. This helps reduce the potential for market volatility causing issues by phasing the entry to the market over a set period.
With that said, it’s also important to consider how much of your wealth you retain in cash savings. While there are long-term benefits to investing your wealth, cash still has an important place in a wider portfolio. We recommend setting aside the equivalent of between one- and three-years’ day-to-day spending in cash, creating a ‘rainy day’ fund for yourself.
Ready to begin your journey with us?
Citations
1 Analysis uses US stock market as data is available for a longer time period than other markets
Past performance is not a guide to future performance and nothing in this article constitutes advice. Although the information and data herein are obtained from sources believed to be reliable, no representation or warranty, expressed or implied, is or will be made and, save in the case of fraud, no responsibility or liability is or will be accepted by Rothschild & Co Wealth Management UK Limited as to or in relation to the fairness, accuracy or completeness of this document or the information forming the basis of this document or for any reliance placed on this document by any person whatsoever. In particular, no representation or warranty is given as to the achievement or reasonableness of any future projections, targets, estimates or forecasts contained in this document. Furthermore, all opinions and data used in this document are subject to change without prior notice.