Global Advisory

Expertenberatung zu M&A und Kapitalmärkten (nur auf Englisch)

Wealth Management

Eine langfristige Perspektive, die Privatkunden dabei unterstützt, ihr Vermögen zu erhalten und auszubauen

Asset Management

Globale Anlagelösungen und Dienstleistungen für institutionelle Kunden, Finanzintermediäre und unabhängige Finanzberater

Five Arrows

Unser Geschäftsbereich für alternative Anlagen, spezialisiert auf Private Equity und Private Debt (Nur auf Englisch)

Über uns

Seit mehr als 200 Jahren im Zentrum der weltweiten Finanzmärkte (nur auf Englisch)

Karriere

Wir stehen für Chancen, unternehmerisches Denken und Wachstum (nur auf Englisch)

Region & Sprache

Region ändern Sprache auswählen

Asset Management: Monthly Macro Insights - January 2024

Veröffentlichungsdatum

Global financial conditions have eased based on confidence that inflation will fall further and central banks will ease their monetary policies without a significant fall in economic activity. This wave of optimism has been boosted by the resilience of the US economy and the surprising shift in the Federal Reserve’s communication. Is the US the canary in the coal mine?

China and the US surprise economists

At the beginning of last year, optimism was high that 2023 would see the Chinese economy rebound strongly. In contrast, the expectation was that the US economy would come under significant pressure from the Fed's sharp increases in interest rates. Yet, as is often the case, this scenario did not proceed as planned.

China's manufacturing PMI ended the year on a very weak note, as decreasing overseas orders and insufficient domestic demand remain key challenges. In the services sector, the index was unchanged at 49.3, the lowest level (bar the pandemic period) since the survey began in 2012, which suggests that consumers remained wary of spending in the midst of anxiety over jobs and the property market.

Conversely, economists have been consistently revising their 2023 US GDP forecasts. Overall, although the US’ outperformance was driven by temporary factors that are unlikely to be repeated, and while GDP weakness likely lies ahead amid the lags of monetary policy, US consumers helped to sustain growth despite the rise in borrowing costs, while China's performance underwhelmed.

Read the full version

The Fed acts as a lone ranger

Headline inflation has come down quickly in most economies over the past year, but core inflation remains some distance from target. In fact, despite falling Q3-23 GDP in most advanced economies, central banks have cautioned monetary policy likely needs to remain restrictive until there are clear signs that underlying inflationary pressures are durably lowered.

In contrast, it seems the Fed decided to execute its much-discussed pivot toward less restrictive monetary policy. Correspondingly, the 2-yr yield, most sensitive to Fed’s policy rate, fell significantly as investors now foresee almost six 25bps cuts in 2024. There was also a dramatic shift for the 10-year Treasury yield which, after almost topping 5 per cent in the wake of the September FOMC meeting, = fell below 4 per cent, reflecting investors’ belief the peak in rates have been reached for this cycle.

Overall, all of this feeds into the ongoing debate over whether inflation was always transitory, or if an immaculate disinflation, i.e. a reduction in inflation without a certain degree of pain on an economy, is possible. The jury is still out.
Read the full version of Monthly Macro Insights - January 2024

by Marc-Antoine Collard, Chief Economist and Head of Economic Research

Read more articles

Bonds, ballots, and the elephant in the room

Markets are navigating geopolitical uncertainty, shifting interest-rate expectations and the rapid expansion of artificial intelligence. Resilient economic activity, healthy corporate profitability and continued technology investment remain supportive, although higher oil prices, rising bond yields and political risks highlight the value of a measured, long-term investment approach.

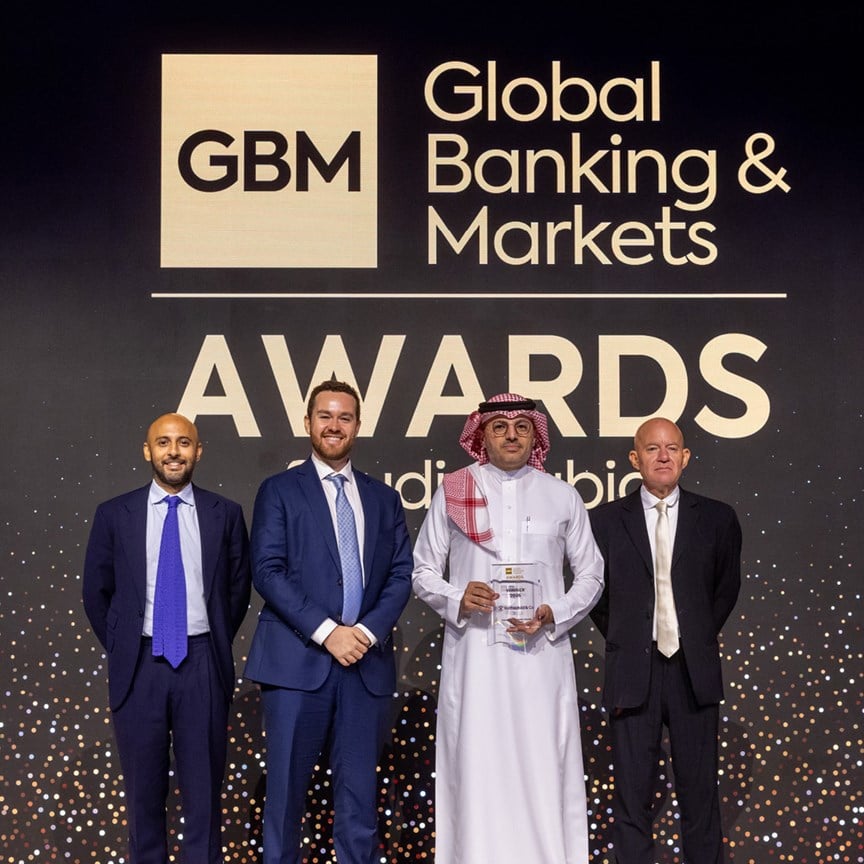
Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Growth Equity Update September 2026 - Edition 54

The latest Growth Equity Update from Patrick Wellington, Vice-Chairman of Equity Advisory.

Asset Management: Monthly Macro Insights - September 2026

Investments linked to artificial intelligence continue to support global growth, but they are also contributing to a sustained rise in long-term interest rates. At the same time, geopolitical tensions and uncertainty surrounding the Federal Reserve’s communication are maintaining a more fragile economic environment.

Back to the future

In recent years, Artificial Intelligence (AI) has taken centre stage, fuelled by spectacular promises and applications that are now very much a reality. We have already noted on several occasions that this revolution is underpinned by less visible building blocks, such as strategic metals, data centres and electricity grids. Recent developments invite us to broaden that perspective even further.

Corporate cash: the decision

Many business owners accumulate cash without a clear strategy. By separating operational, reserve and surplus capital, businesses can improve resilience, reduce concentration risk, manage tax considerations more effectively, and ensure excess cash supports longer-term business and personal objectives.