Mehr entdecken
Kontakt

Global Advisory

Expertenberatung zu M&A und Kapitalmärkten (nur auf Englisch)

Wealth Management Schweiz

Eine langfristige Perspektive, die Privatkunden dabei unterstützt, ihr Vermögen zu erhalten und auszubauen

Asset Management

Globale Anlagelösungen und Dienstleistungen für institutionelle Kunden, Finanzintermediäre und Berater entsprechen

Five Arrows

Unser Geschäftsbereich für alternative Anlagen, spezialisiert auf Private Equity und Private Debt (Nur auf Englisch)

Über uns

Seit mehr als 200 Jahren im Zentrum der weltweiten Finanzmärkte (nur auf Englisch)

Karriere

Wir stehen für Chancen, unternehmerisches Denken und Wachstum (nur auf Englisch)

Region und Sprache

Region ändern Sprache auswählen

Asset Management: Monthly Macro Insights - March 2024

Veröffentlichungsdatum

Global growth resilience expected in 2024 masks the continuation of sharp regional divergences. Although headline inflation in most G20 countries is projected to continue its normalisation, it is unlikely to be back to target before the end of 2025, and upside risks remain elevated. In fact, central banks may be forced to remain prudent to ensure that underlying inflationary pressures are durably contained.

Challenges for the US…

Last year, growth was particularly buoyant in the US amid high government spending and strong household consumption. However, after two years of pent-up demand, fuelled in part by surging credit card debt, massive government stimulus and the run-down of the excess savings accumulated since the beginning of the pandemic, the consumption engine may lose steam this year despite lower inflation strengthening real wage growth. Meanwhile, even though investors seem to underplay the downside risks for the US economy, inflation has generally surprised to the upside.

Read the full version

…and for the Eurozone

At the end of 2023, Eurozone GDP was broadly at the same level as in the third quarter of 2022. Contrary to the US, consumption and investment barely moved last year, while the weak positive contribution to growth of external demand was driven by imports falling more than exports.

Looking ahead, the European Commission economic sentiment index unexpectedly fell in February, suggesting no imminent rebound in GDP amid the fastest tightening cycle in the history of the Eurozone. In addition, the ECB could upset investors’ hopes of significant rate cuts in 2024. The inflation surprised to the upside in February and, more fundamentally, the combination of mediocre productivity and elevated wage growth implies the unit labour cost growth remains above rates compatible with medium-term inflation objectives.

Murky outlook in China

The growth target and macroeconomic policy stance have been revealed at the National People’s Congress. The 2024 growth target was set at 5 per cent, the same as in 2023, though this will be much harder to achieve given the more challenging base effect. By setting the bar high for this year, the authorities might have signalled their plans to provide stronger support for the economy, or instead tried to boost consumer and business confidence.
Read the full version of Monthly Macro Insights - March 2024

by Marc-Antoine Collard, Chief Economist and Head of Economic Research

Read more articles

Bonds, ballots, and the elephant in the room

Markets are navigating geopolitical uncertainty, shifting interest-rate expectations and the rapid expansion of artificial intelligence. Resilient economic activity, healthy corporate profitability and continued technology investment remain supportive, although higher oil prices, rising bond yields and political risks highlight the value of a measured, long-term investment approach.

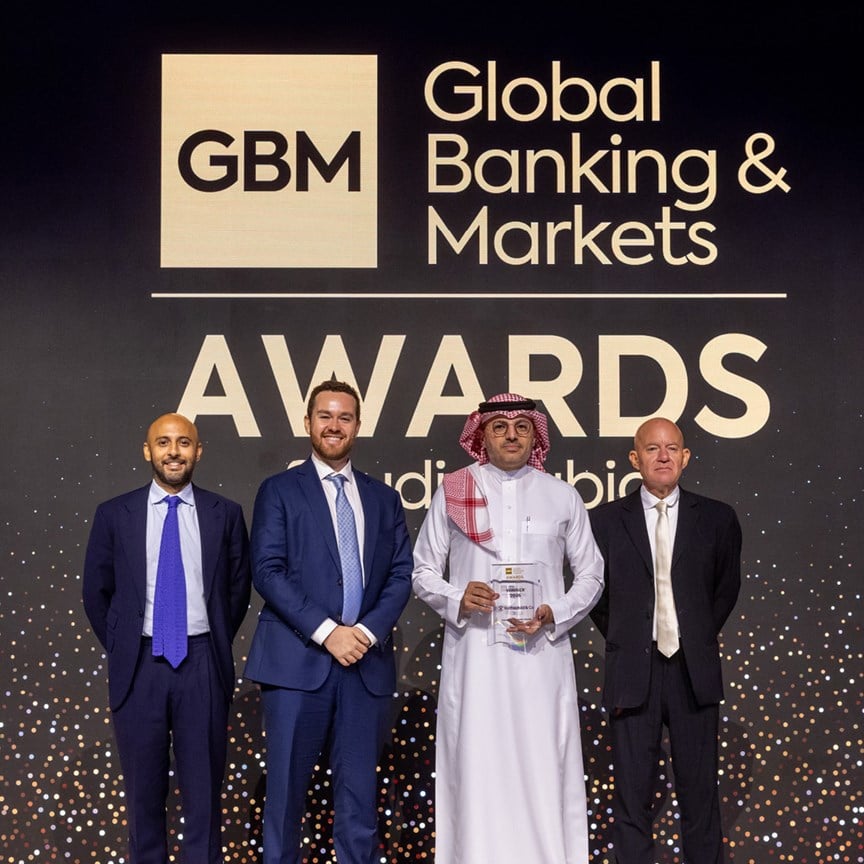
Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Growth Equity Update September 2026 - Edition 54

The latest Growth Equity Update from Patrick Wellington, Vice-Chairman of Equity Advisory.

Asset Management: Monthly Macro Insights - September 2026

Investments linked to artificial intelligence continue to support global growth, but they are also contributing to a sustained rise in long-term interest rates. At the same time, geopolitical tensions and uncertainty surrounding the Federal Reserve’s communication are maintaining a more fragile economic environment.

Back to the future

In recent years, Artificial Intelligence (AI) has taken centre stage, fuelled by spectacular promises and applications that are now very much a reality. We have already noted on several occasions that this revolution is underpinned by less visible building blocks, such as strategic metals, data centres and electricity grids. Recent developments invite us to broaden that perspective even further.

Corporate cash: the decision

Many business owners accumulate cash without a clear strategy. By separating operational, reserve and surplus capital, businesses can improve resilience, reduce concentration risk, manage tax considerations more effectively, and ensure excess cash supports longer-term business and personal objectives.