Kontakt

Global Advisory

Expertenberatung zu M&A und Kapitalmärkten (nur auf Englisch)

Wealth Management

Eine langfristige Perspektive, die Privatkunden dabei unterstützt, ihr Vermögen zu erhalten und auszubauen

Asset Management

Globale Anlagelösungen und Dienstleistungen für institutionelle Kunden, Finanzintermediäre und unabhängige Finanzberater

Five Arrows

Unser Geschäftsbereich für alternative Anlagen, spezialisiert auf Private Equity und Private Debt (Nur auf Englisch)

Über uns

Seit mehr als 200 Jahren im Zentrum der weltweiten Finanzmärkte (nur auf Englisch)

Karriere

Wir stehen für Chancen, unternehmerisches Denken und Wachstum (nur auf Englisch)

Region & Sprache

Region ändern Sprache auswählen

Asset Management: Monthly Macro Insights - January 2025

Veröffentlichungsdatum

In 2024, global growth has remained stable and world trade has been recovering, while price pressures continued to ebb. Investors project that this resilience will continue in 2025, with inflation further converging towards central banks’ targets. However, this outlook masks significant differences across sectors and countries, and is surrounded by important uncertainties.

Downside risks in the US…

The global economy has proved resilient in the last year, but is in large part explained by the US which experienced the fastest GDP growth in all G7 countries in the past two years and this exceptionalism would persist this year according to the latest OECD economic projections. Yet, while the recent pattern of unexpected US resilience could continue, risks are nonetheless skewed to the downside.

Read the full version

… and Europe

Economic growth in Europe has been mediocre in 2024, as GDP probably expanded less than 1 per cent in the UK and the Eurozone. Looking ahead, recent indicators suggest ongoing weakness with the PMI business confidence index, hovering around the neutral 50-threshold at the end of 2024, thus flagging downside risks to investors’ sanguine forecasts.

China’s murky outlook

Since the end of September, China’s growth has shown some tentative signs of steadying due to the recent policy push. For instance, the decline in house prices across major cities slowed in November for the first time since early 2024, although retail sales growth unexpectedly weakened. Inflation decelerated in November to a mere 0.2 per cent from 0.3 per cent, a sign that the domestic economy remains fragile. The government is expected to unleash more measures, but the extent of the support will likely be adjusted depending on the degree of the external drag.
Read the Monthly Macro Insights - January 2025

by Marc-Antoine Collard, Chief Economist and Head of Economic Research

Read more articles

Bonds, ballots, and the elephant in the room

Markets are navigating geopolitical uncertainty, shifting interest-rate expectations and the rapid expansion of artificial intelligence. Resilient economic activity, healthy corporate profitability and continued technology investment remain supportive, although higher oil prices, rising bond yields and political risks highlight the value of a measured, long-term investment approach.

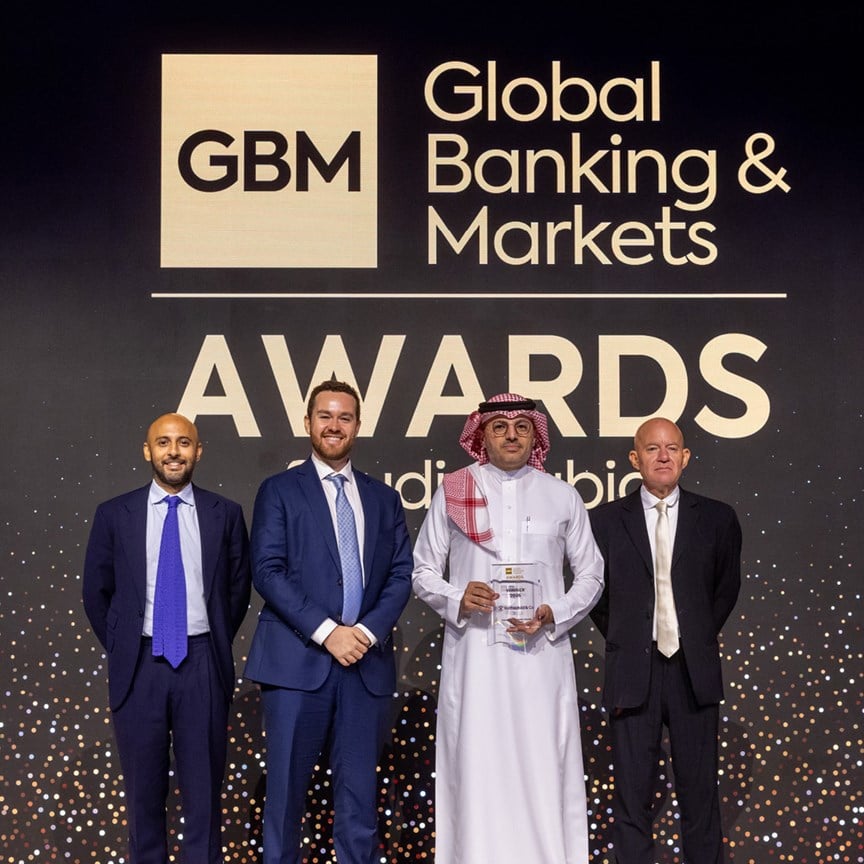
Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Rothschild & Co has been recognised across five categories at the Global Banking & Markets Awards in the Middle East

Growth Equity Update September 2026 - Edition 54

The latest Growth Equity Update from Patrick Wellington, Vice-Chairman of Equity Advisory.

Asset Management: Monthly Macro Insights - September 2026

Investments linked to artificial intelligence continue to support global growth, but they are also contributing to a sustained rise in long-term interest rates. At the same time, geopolitical tensions and uncertainty surrounding the Federal Reserve’s communication are maintaining a more fragile economic environment.

Back to the future

In recent years, Artificial Intelligence (AI) has taken centre stage, fuelled by spectacular promises and applications that are now very much a reality. We have already noted on several occasions that this revolution is underpinned by less visible building blocks, such as strategic metals, data centres and electricity grids. Recent developments invite us to broaden that perspective even further.

Wealth Management: Märkte & Trends September

Die Spannungen im Nahen Osten bleiben hoch. Nachdem eine Waffenruhe zwischen den USA und dem Iran Anfang Juli zusammengebrochen war, wurden die Angriffe zunächst wieder aufgenommen.