Beyond the noise: investing across generations
Earlier this month Rothschild & Co Wealth Management UK were delighted to welcome members of our trusted professional adviser network for a breakfast in our New Court offices in London.
During the breakfast, we heard from Client Advisers Katharine Taylor and James Peterson, alongside Global Investment Strategist Victor Balfour, Portfolio Manager Rupen Patel and our Head of Private Client Wealth Solutions David Kilshaw.
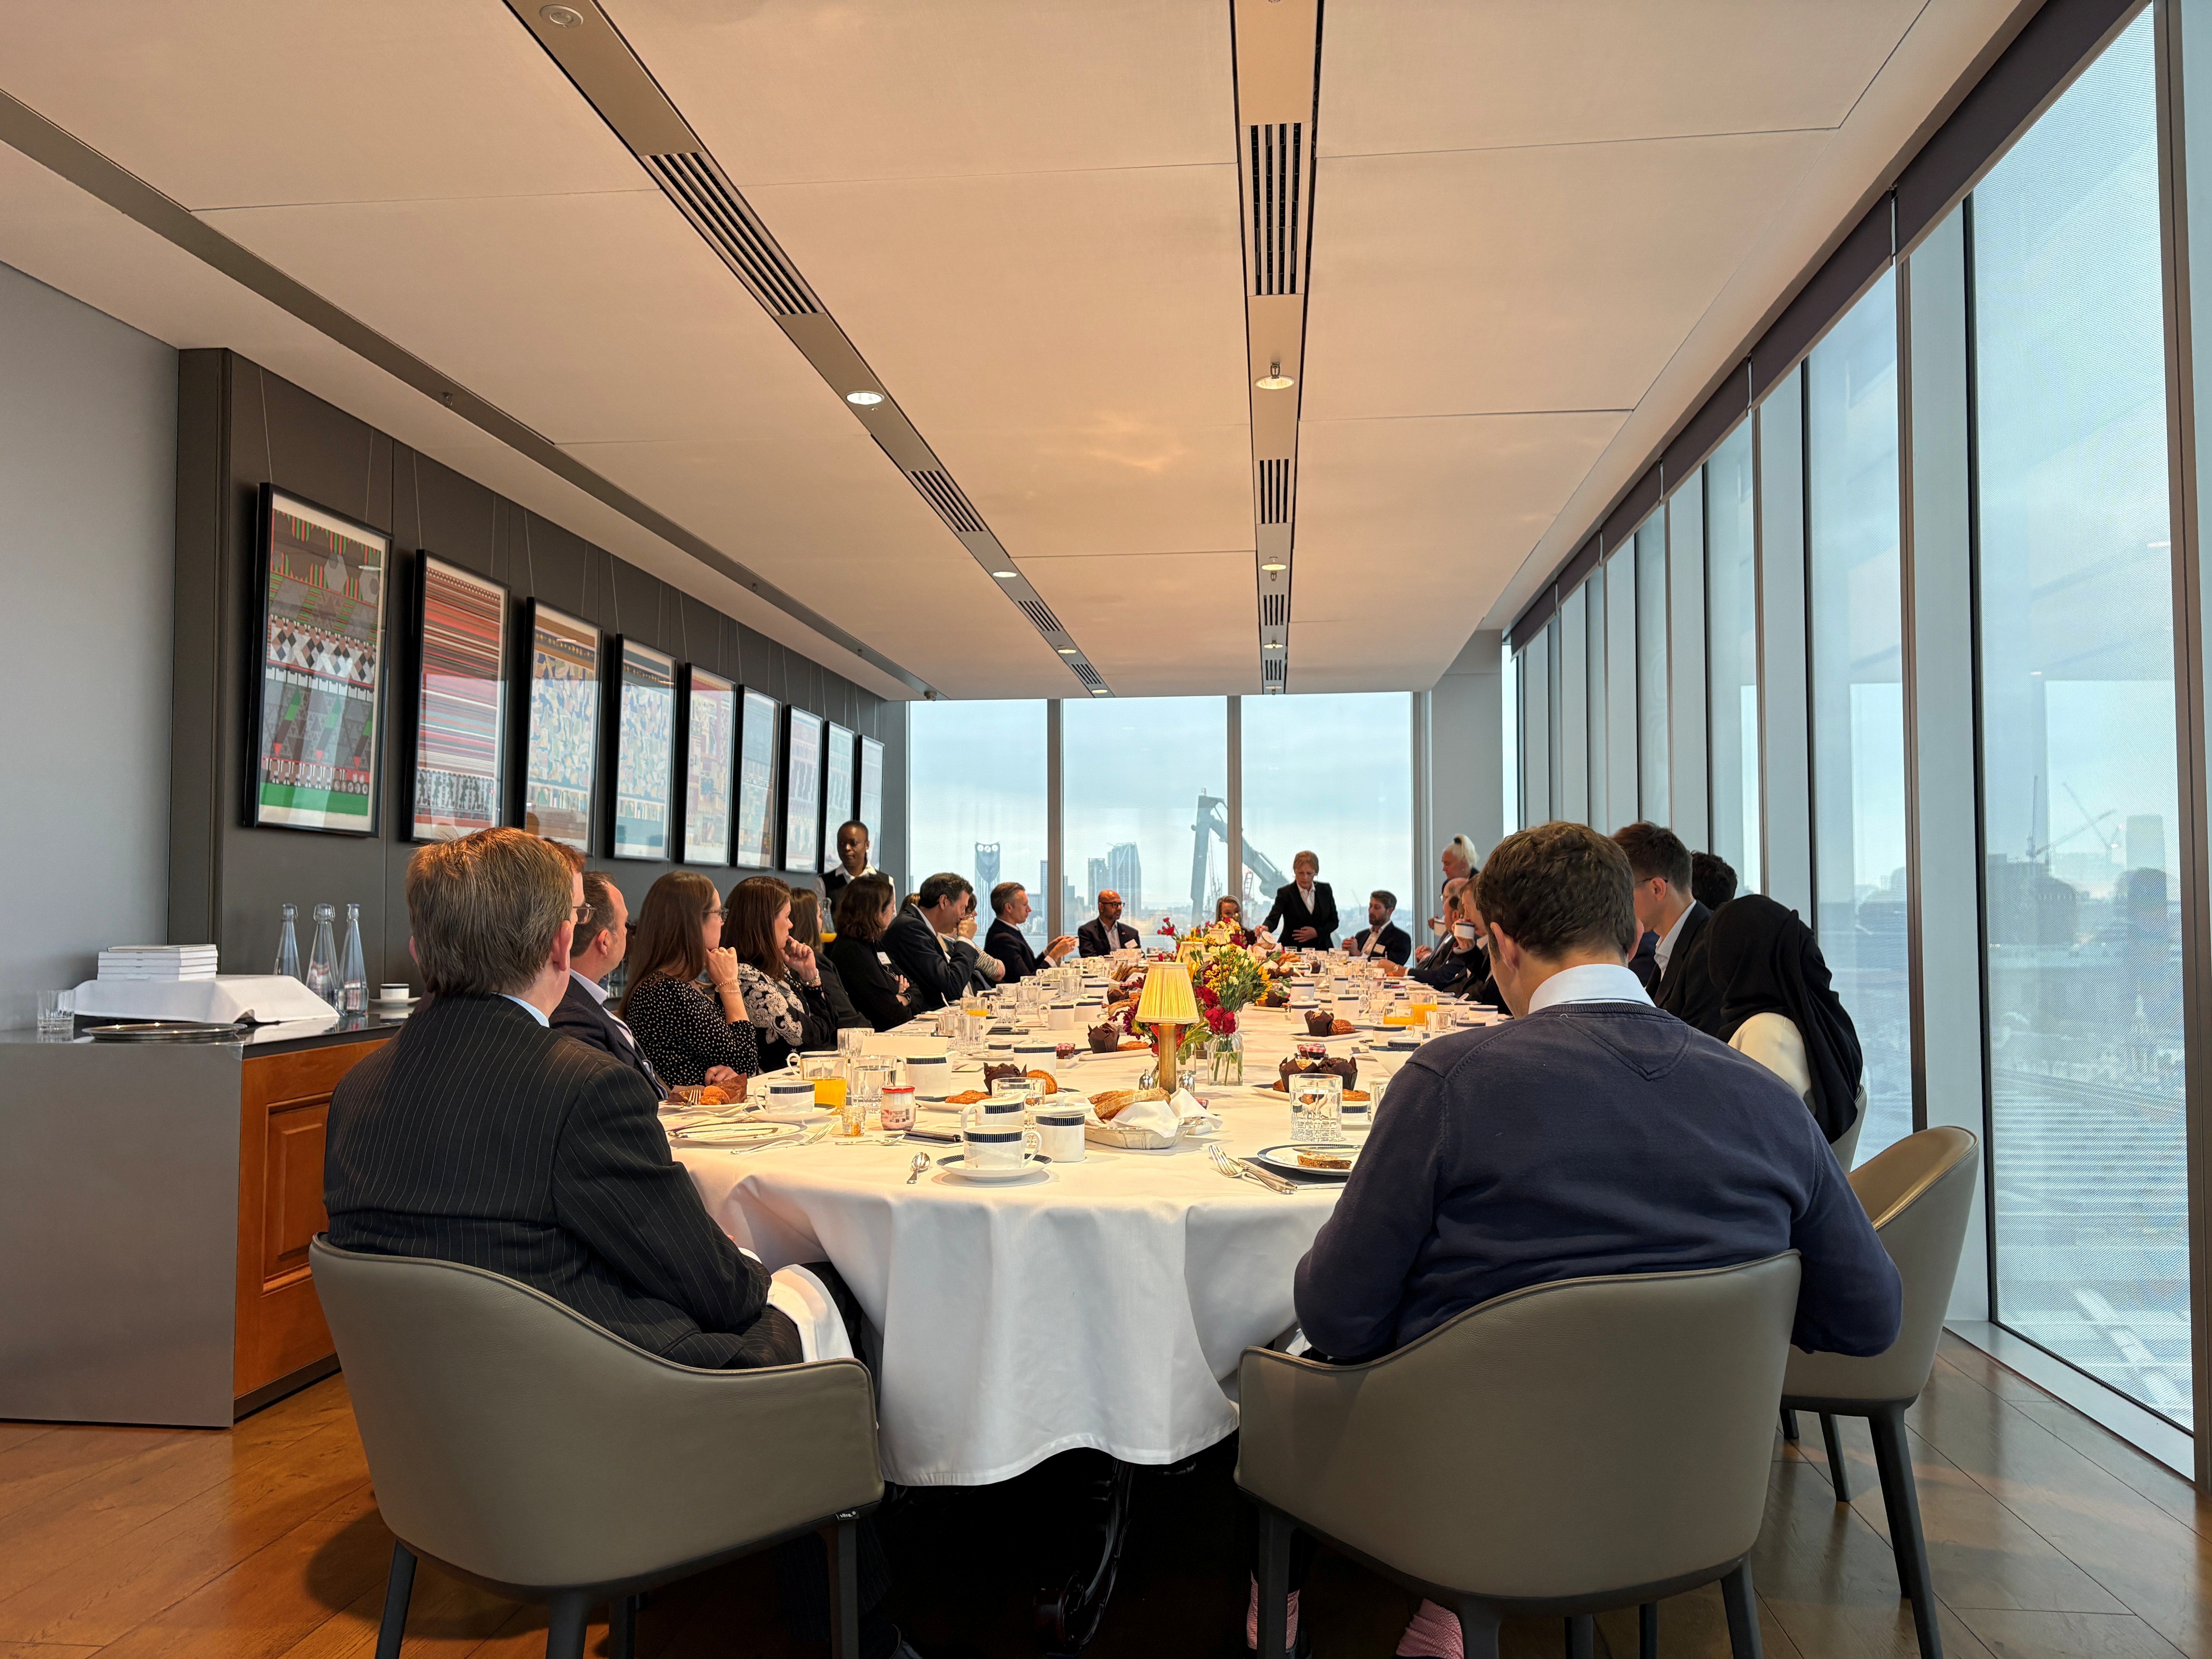
The theme for the morning was investing across generations. For many families, one of the biggest challenges is trying to generate attractive returns while protecting wealth and preserving their purchasing power. The right investment strategy can serve the needs of the family both today and for generations to come.
As a multigenerational business ourself, this is a challenge we understand. We see our role as being the guardian of our clients’ nest eggs, taking a genuinely long-term view of capital. Rather than responding to short-term market noise, our focus continues to be on what helps families achieve their goals over decades.
Yet there are many ways to approach multigenerational investing. At breakfast, we spent time discussing with our professional adviser network three areas in particular : diversification, passive investing and private markets.
Rethinking diversification
Diversification has long been a fundamental principle of portfolio construction. Spreading investments across different assets can help reduce an investor's reliance on any single source of return.
However, diversification for diversification’s sake doesn't necessarily reduce risk."
Portfolios can become increasingly complex, particularly when they are divided between multiple asset classes, managers and investment structures. On the surface, this gives the appearance of diversification, but how do those investments actually behave when conditions become difficult?
During periods of market stress, it is not uncommon for assets that normally appear uncorrelated to begin moving in the same direction. In other words, simply owning more investments doesn't automatically mean your sources of return are genuinely diversified.
So, the key question isn't, “How many different assets do we need to own?” Instead, it should be: “Which assets will behave differently when we need them to?”
The upshot is that complexity needs a clear purpose. Having more portfolios, more managers or more investments does not inherently produce better outcomes, and it is often the case that additional complexity benefits the product seller more than the product buyer.
Passive investing is still an active decision
Passive investing has become an important part of the investment landscape, offering simplicity, transparency and relatively low costs. But passive investing doesn't remove the need for good judgement.
Investors still need to decide which market or index they want to track, and that decision ultimately determines where their capital is exposed.
This is particularly important when markets become very concentrated. An index may contain hundreds or thousands of businesses, but a significant proportion of its economic exposure is being driven by a relatively small number of companies or sectors. Again, in cases such as this, investors may end up less diversified than they think.
There is also a behavioural dimension to consider. A passive investment strategy still requires investors to hold their nerve when markets fall sharply. After all, passive investing doesn't reduce volatility or improve the risk characteristics of portfolios.
Understanding the underlying drivers of return and risk therefore remains essential, whether your investments are managed actively or passively."
Beneath the surface of private markets
Private markets can provide access to companies, assets and strategies unavailable through public markets. As such a good manager can generate attractive long-term returns by selecting the right blend at the right price.
However, investors also need to understand what they are giving up in return.
Liquidity is an obvious consideration, as investors' capital can be tied up for many years. The costs and investment structures involved may also be more complex, and access to the strongest managers is not always straightforward.
Fees can be significantly higher and not always fully disclosed. They can also be levied on committed capital before it’s deployed, further impacting the net-of-fee returns than might be obvious at the outset.
Less frequent pricing can also create an impression of stability. A private asset whose value is assessed periodically will naturally display a smoother return profile than a listed security priced continuously. However a smoother reported price does not necessarily mean lower underlying economic risk.
The analogy of a family home is useful. If its market value appeared updated on a homeowner's phone every afternoon, they would probably see residential property as considerably more volatile than they do today.
Private markets can play an important role in an investment approach, but their risks should be assessed on their economic substance and net -of-fees performance rather than the apparent smoothness of reported returns and optically ambitious gross Internal Rates of Return (IRRs).
Start with the purpose of capital
The observations expressed here do not mean that asset allocation, passive investing or private markets are inherently right or wrong. Each has its own merits, depending on an investor's circumstances.
The more fundamental question is what the capital is there to achieve.
For many families investing across generations, that means considering how to protect against the permanent loss of wealth, while preserving purchasing power and participating meaningfully in long-term economic growth. Crucially, families should avoid taking unnecessary risks in doing so (permanent capital losses are irrecoverable).
This encourages a focus on the underlying drivers of return, the distinction between return-generating and diversifying assets, and the extent to which every layer of complexity genuinely improves the portfolio. Less complexity can provide greater clarity and a reduced fee drag for families taking a long-term view.
Ultimately, successful multigenerational investing is not about owning the greatest number of investments or following the most sophisticated framework. It's about understanding what you own, why you own it and the role each investment plays.
The careful use and selection of a “tax wrapper” can also support a philosophy of investing for the longer terms. Investments can benefit from compound growth from rolled up capital gains. “Wrappers” can also enable fees to be paid from gross income (which may be particularly advantageous given the forthcoming 49% tax rate on savings income), have VAT advantages and ease tax reporting.
There are a variety of appropriate wrappers including offshore bonds, family investment companies, open-ended investment companies (such as our New Court Fund) and private unit trusts/OEICs.
We would like to thank everyone who joined us for the breakfast and contributed to such a thoughtful discussion. We look forward to building on these conversations and continuing to work closely with our professional adviser network.
Past performance is not a guide to future performance and nothing in this article constitutes advice. Although the information and data herein are obtained from sources believed to be reliable, no representation or warranty, expressed or implied, is or will be made and, save in the case of fraud, no responsibility or liability is or will be accepted by Rothschild & Co Wealth Management UK Limited as to or in relation to the fairness, accuracy or completeness of this document or the information forming the basis of this document or for any reliance placed on this document by any person whatsoever. In particular, no representation or warranty is given as to the achievement or reasonableness of any future projections, targets, estimates or forecasts contained in this document. Furthermore, all opinions and data used in this document are subject to change without prior notice.