AI jitters return
AI fragility has returned, with markets once again vacillating between boom and doom over the scale of AI-related financing.
After a very narrow and divided stock market in September, when the median US stock fell nearly 5% while the technology sector rose 4%, October has been almost a complete mirror image. Over the past three weeks, a basket of semiconductor stocks has dropped more than 15%, while the highly concentrated South Korean index has fallen back nearly 20%.
Selected equity market relative returns: 2026 YTD (USD terms)
Market capitalisation weighted index relative to equal weighted index returns
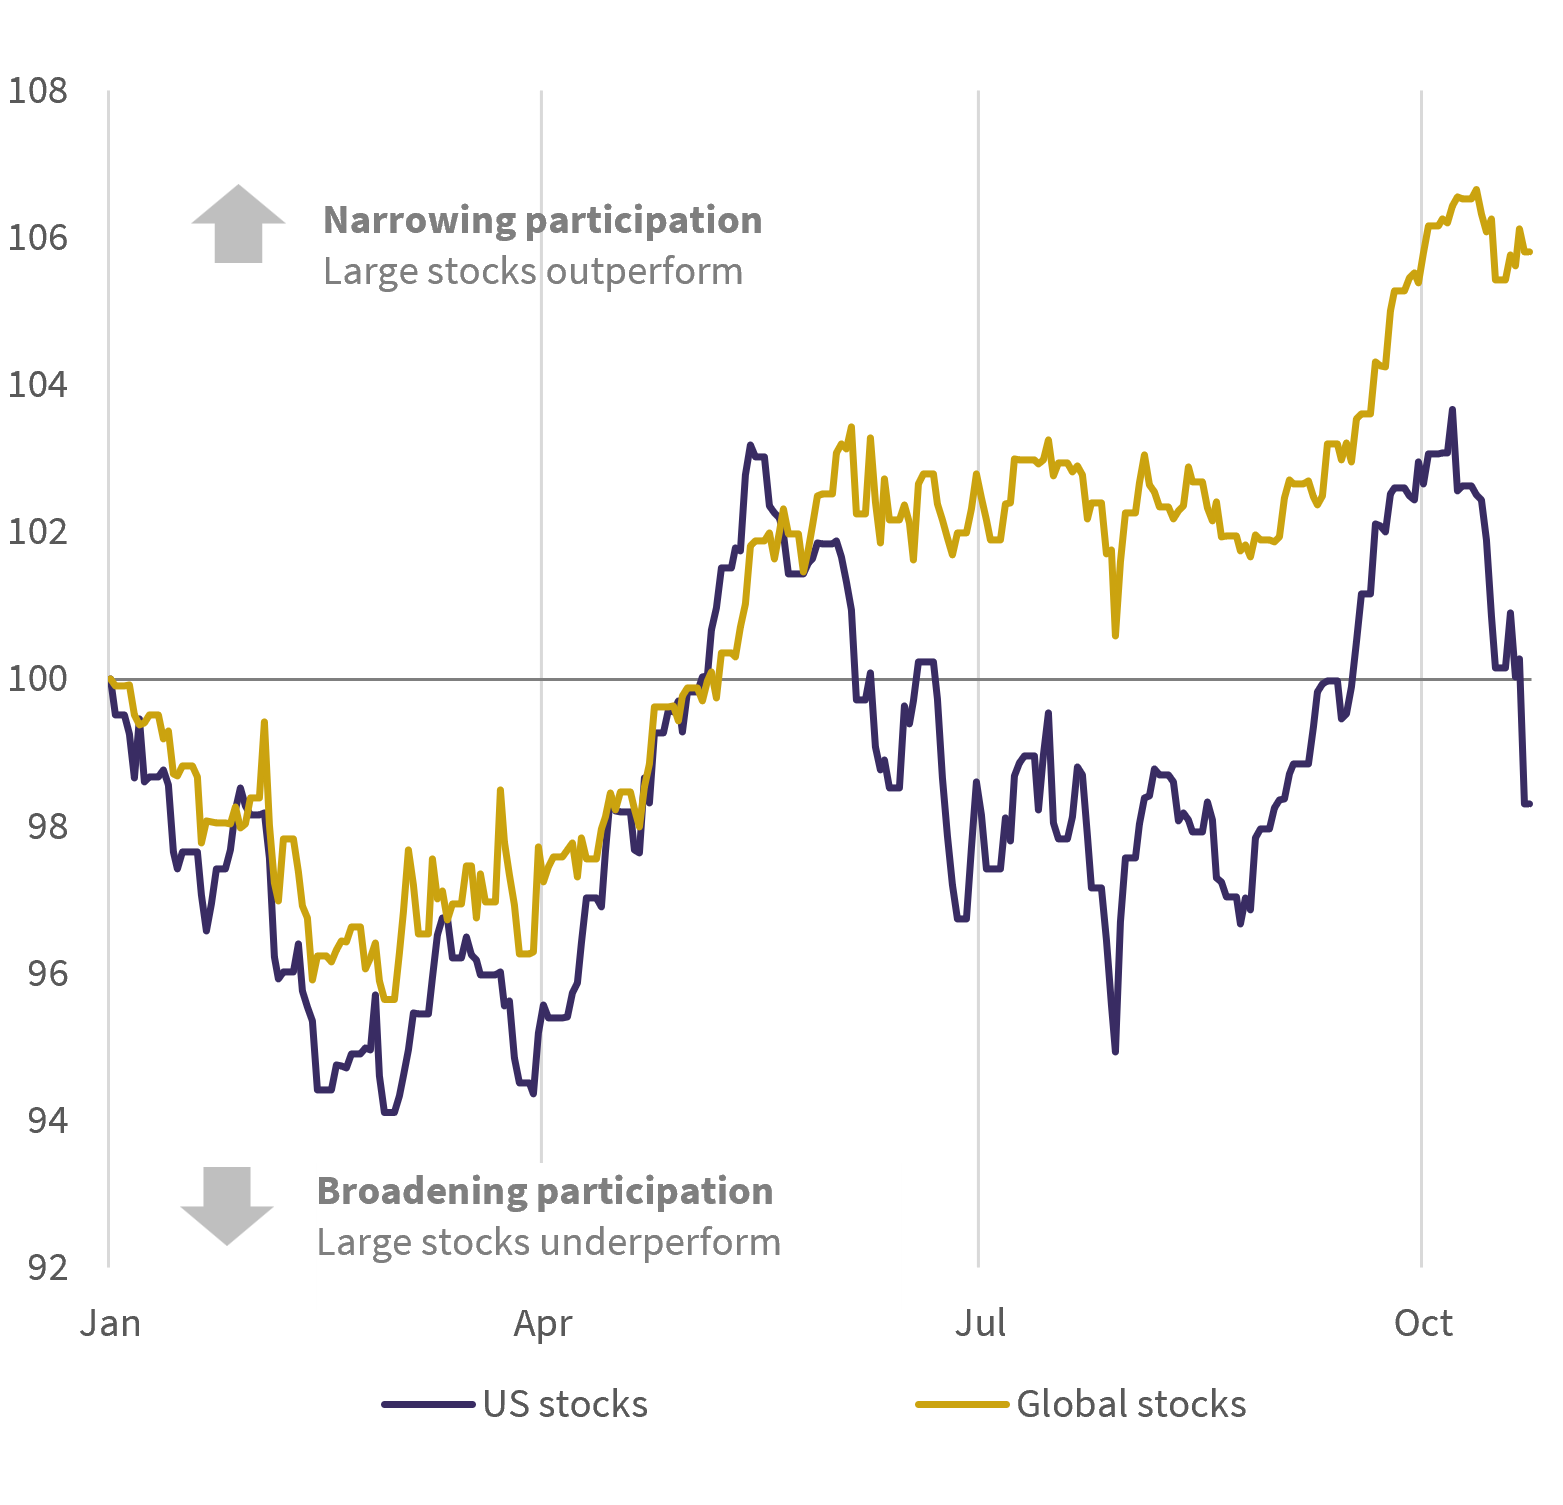
Source: Rothschild & Co, Bloomberg, S&P Global. Correct to 22 October 2026
This fragility has also extended to credit markets, where the yield 'spread' over government borrowing costs has widened to its highest level since the spring. Some of this widening is likely explained by the rally in government bonds, with which corporate borrowing costs have not kept pace. The strong positive correlation between oil prices and bond yields has broken down in recent days: Brent has been grinding higher through October ($116/barrel as we write, up 13% this month), yet US Treasuries had their biggest one-day rally in more than three years yesterday, with the 10-year yield falling back by ~30bps since the start of the month.
This latest AI rout seems to be less about deteriorating fundamentals – third-quarter earnings have provided some comfort (at least so far). Anxiety is most visible in the highly leveraged segment of the AI ecosystem.
AI cloud providers, the so-called neocloud companies, are at the bleeding edge of this rotation today. This cohort has roughly halved since its June highs, and most are now down year to date. Even for AI optimists, these specialised compute providers are a brave proposition: CoreWeave, perhaps the best-known, has around eight turns of debt and a revenue stream heavily concentrated among a handful of customers, led by Microsoft and OpenAI. A highly leveraged owner-operator of potentially fast-obsolescing assets, with an ambiguous revenue runway. What could go wrong?
While there are undoubtedly vulnerabilities within the AI story, the notion that we are at some sort of inflection point may also be premature. As the chart above shows, we have seen this rotation between the largest stocks (dominated by technology names) and the wider market twice in 2026 alone.
For the most part, the more highly geared AI companies make up a relatively small share of the equity and debt markets. Meanwhile, the hyperscalers – which comprise a non-trivial weighting in the wider index – have proved much more defensive through this volatility. That applies to their share prices as well as, relatively speaking, their credit spreads. Strong operating cash flows and even stronger balance sheets (despite rising debt issuance) provide a reassuring backstop should wider financing concerns become more visible.
Sind Sie bereit, Ihre Reise mit uns zu beginnen?
Sprechen Sie mit einem Kundenberater in Grossbritannien oder in der Schweiz.
Past performance is not a guide to future performance and nothing in this article constitutes advice. Although the information and data herein are obtained from sources believed to be reliable, no representation or warranty, expressed or implied, is or will be made and, save in the case of fraud, no responsibility or liability is or will be accepted by Rothschild & Co Wealth Management UK Limited as to or in relation to the fairness, accuracy or completeness of this document or the information forming the basis of this document or for any reliance placed on this document by any person whatsoever. In particular, no representation or warranty is given as to the achievement or reasonableness of any future projections, targets, estimates or forecasts contained in this document. Furthermore, all opinions and data used in this document are subject to change without prior notice.