The Midterms
The election is upon us, and a Democratic clean sweep has moved further into focus. This midterm cycle has been marked by hyperbolic promises, a bad-tempered debate and an electorate worn down by inflation. Trump's approval has fallen to a record low of 31% (at least by one poll), and the Democrats’ lead over the GOP – ahead by 9 points (52% to 43%) in generic congressional polling – continues to widen.
The House arithmetic is very finely balanced: the Democrats need a net gain of five seats to command a majority. Control of the lower chamber would give the Democrats the power to impeach, though not to remove, the president, and a significant leverage over the budget. With government funding expiring on 11th December, the annual fiscal showdown is likely to be more fraught than usual. The Senate is a closer contest: Democrats need a net gain of four seats, which means winning in Republican-leaning states.
Whether a blue wave or a blue ripple follows, much of the administration's agenda, including tariffs, deregulation and foreign policy, has been set by the executive branch (that is, without Congressional approval) and would continue regardless. This may be of little consolation given the current state of affairs.
Nonetheless, the market impact of more political gridlock is likely overstated. In the post-war period the S&P 500 has risen in the 12 months after every midterm, by about 15% on average, against 9% for a typical 12-month period. Similarly, a president’s party ceding control of congress – divided or otherwise - has not been a threat to markets, though in the case of the former, the range of outcomes has been wider.
S&P 500 index return after each midterm: next twelve months
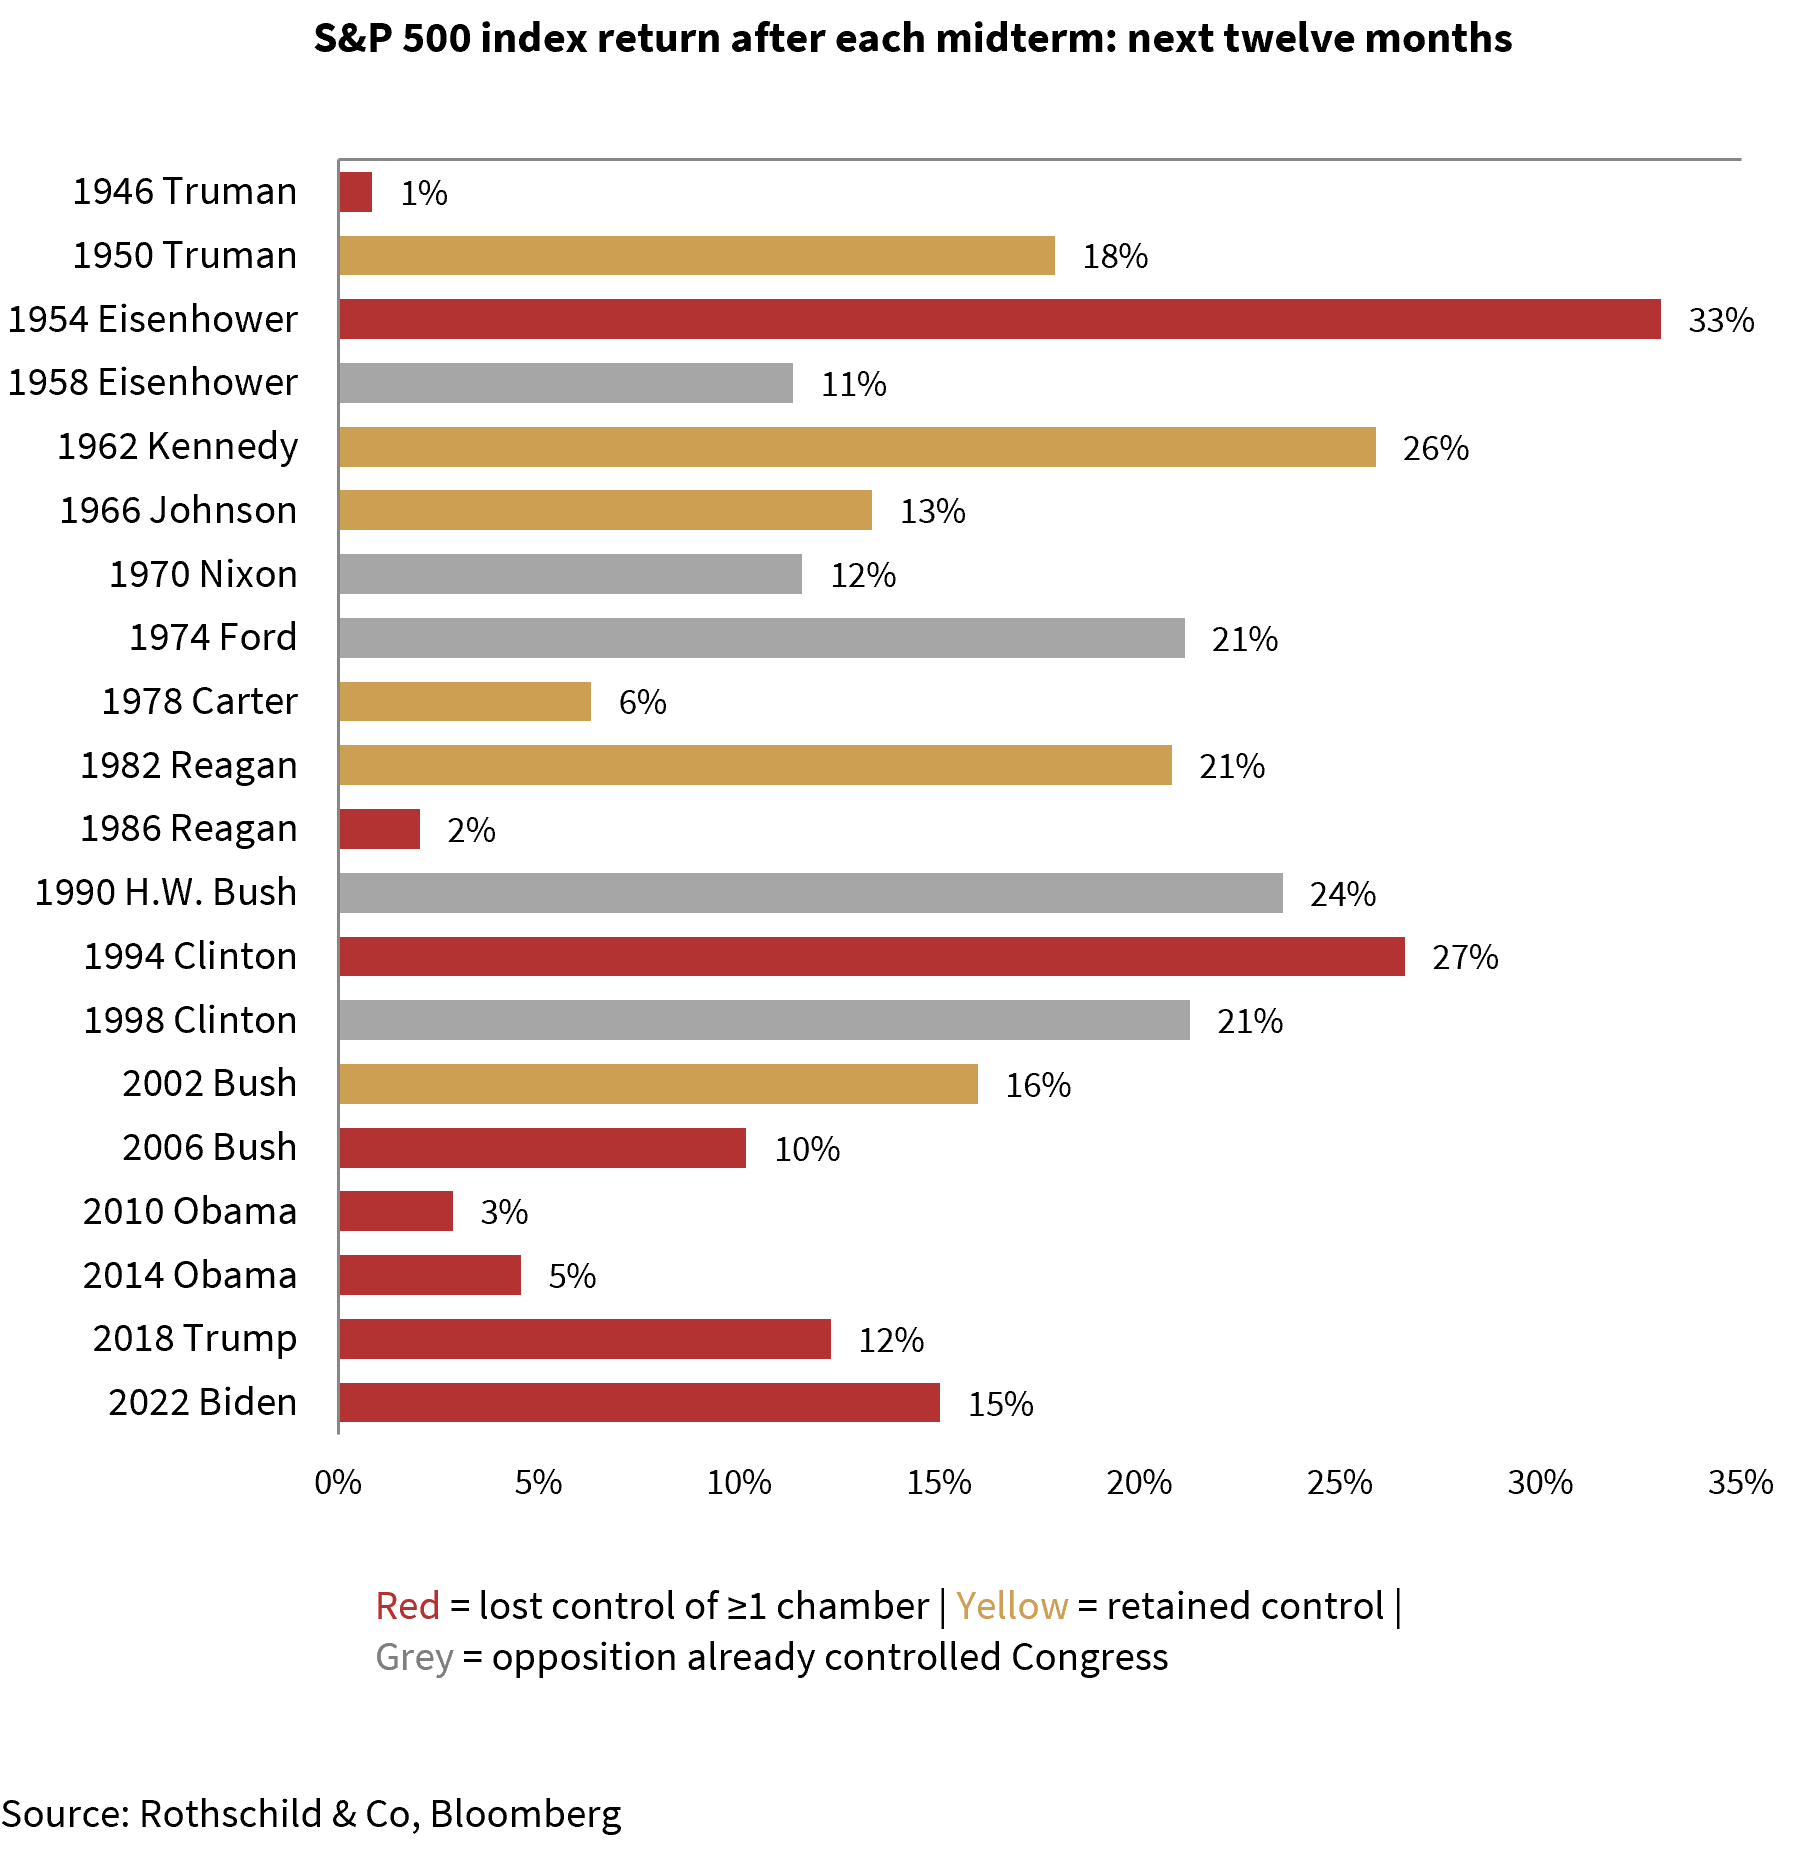
Of course, past performance is no guide to future performance and context is hugely important. The weakest post-midterm years were driven by shocks unrelated to the vote: the 1987 crash, the 2011 US downgrade, and the 2015 China devaluation.
The machinations of US politics are complex and nuanced. We are not political experts, nor can we disentangle every possible policy permutation, so it would be folly to try to translate the many possible outcomes into specific investment advice. Our assessment is that neither a Democrat-controlled or divided Congress is likely to derail the growth trajectory for the US economy, which is underpinned by a corporate sector that continues to deliver record profitability, a resilient consumer and nascent revival in the manufacturing sector. Even the possibility of more restrictive fiscal policy alongside rising US rates – which are only moving higher very gradually – are manageable. Strong economic growth continues and that is the more important driver of the investment climate.
Ready to begin your journey with us?
Speak to a Client Adviser in the UK or Switzerland
Past performance is not a guide to future performance and nothing in this article constitutes advice. Although the information and data herein are obtained from sources believed to be reliable, no representation or warranty, expressed or implied, is or will be made and, save in the case of fraud, no responsibility or liability is or will be accepted by Rothschild & Co Wealth Management UK Limited as to or in relation to the fairness, accuracy or completeness of this document or the information forming the basis of this document or for any reliance placed on this document by any person whatsoever. In particular, no representation or warranty is given as to the achievement or reasonableness of any future projections, targets, estimates or forecasts contained in this document. Furthermore, all opinions and data used in this document are subject to change without prior notice.