France: Fiscal pressure
And so, the mantle of political instability passes from the UK to Europe. Spain is heading for a snap election after Pedro Sánchez called an early vote, but it is France which continues to steal the show.
French assets have come under renewed pressure. France’s CAC 40 stock index has fallen into correction territory (a ~10% fall since early August), and long-term French borrowing costs are not far from the psychologically relevant 5% level. Government bond yields have been rising across the developed world, but French OAT yields have been rising by more: the 10-year OAT–Bund spread widened to ~140 bps – a level not seen since the depths of the eurozone debt crisis. Meanwhile, the euro is flirting with 17-month lows.
Once again, concerns over the sustainability of France’s fiscal position are being amplified by social tensions and the prospect of a more fragmented – and less cooperative – government.
France is no stranger of late to political instability. Emmanuel Macron has been president for nearly a decade, but he has cycled through a succession of minority governments since the parliamentary snap election in June 2024. It seemed likely that political risk would resurface as the government attempted to pass its 2027 budget, against a backdrop of looming political change. But even we are a little surprised by the extent to which France has been singled out.
Two issues seem to have aggravated the bond market. The first is fiscal slippage: the French government will not meet its previous public deficit target of 5% of GDP in 2026 – that ambition has been deferred to 2027. The second is uncertainty over the 2027 presidential election, as support for the political centre ground fades further in the latest polls.
The first issue is serious, but not insurmountable. The latest proposed 2027 budget includes further spending restraint but seems unlikely to reach a parliamentary consensus. While this raises the possibility of yet another year-end ‘no confidence’ vote, the more likely pathway is a modified budget that will be pushed through under Article 49.3, which avoids a formal vote.
The second, slightly more difficult issue is what follows in 2027. Marine Le Pen remains the presidential frontrunner, with her legal headwinds now largely resolved. But her victory would not determine the composition of the National Assembly, where there is growing possibility of a hung parliament dominated by mutually hostile blocs, including the National Rally and Jean-Luc Mélenchon’s leftist France Unbowed (LFI) party. Le Pen appears committed to fiscal discipline, but largely via spending cuts aimed at immigration and non-citizen welfare – which would not land well in Brussels. However, Mélenchon rejects consolidation outright, proposing to ‘restructure’ (cancel?) debt and tax the wealthy to fund higher wages, pensions, and public spending, again in open defiance of EU fiscal rules.
As we’ve noted before, France’s fiscal position is stretched, but not entirely unique. At the end of 2025, five EU countries – Greece, Italy, France, Belgium, and Spain – had gross government debt above 100% of GDP. Italy and Greece carried even larger debt stocks relative to their economies. Where France’s position is more difficult is in the combination of a high debt ratio, a relatively large deficit – similar to those of the US and UK – and a divided political landscape. The size of France's government is also particularly big – public spending is equivalent to almost three-fifths of GDP.
Government Deficit & Debt: France, Europe and the G7 (full-year 2025)
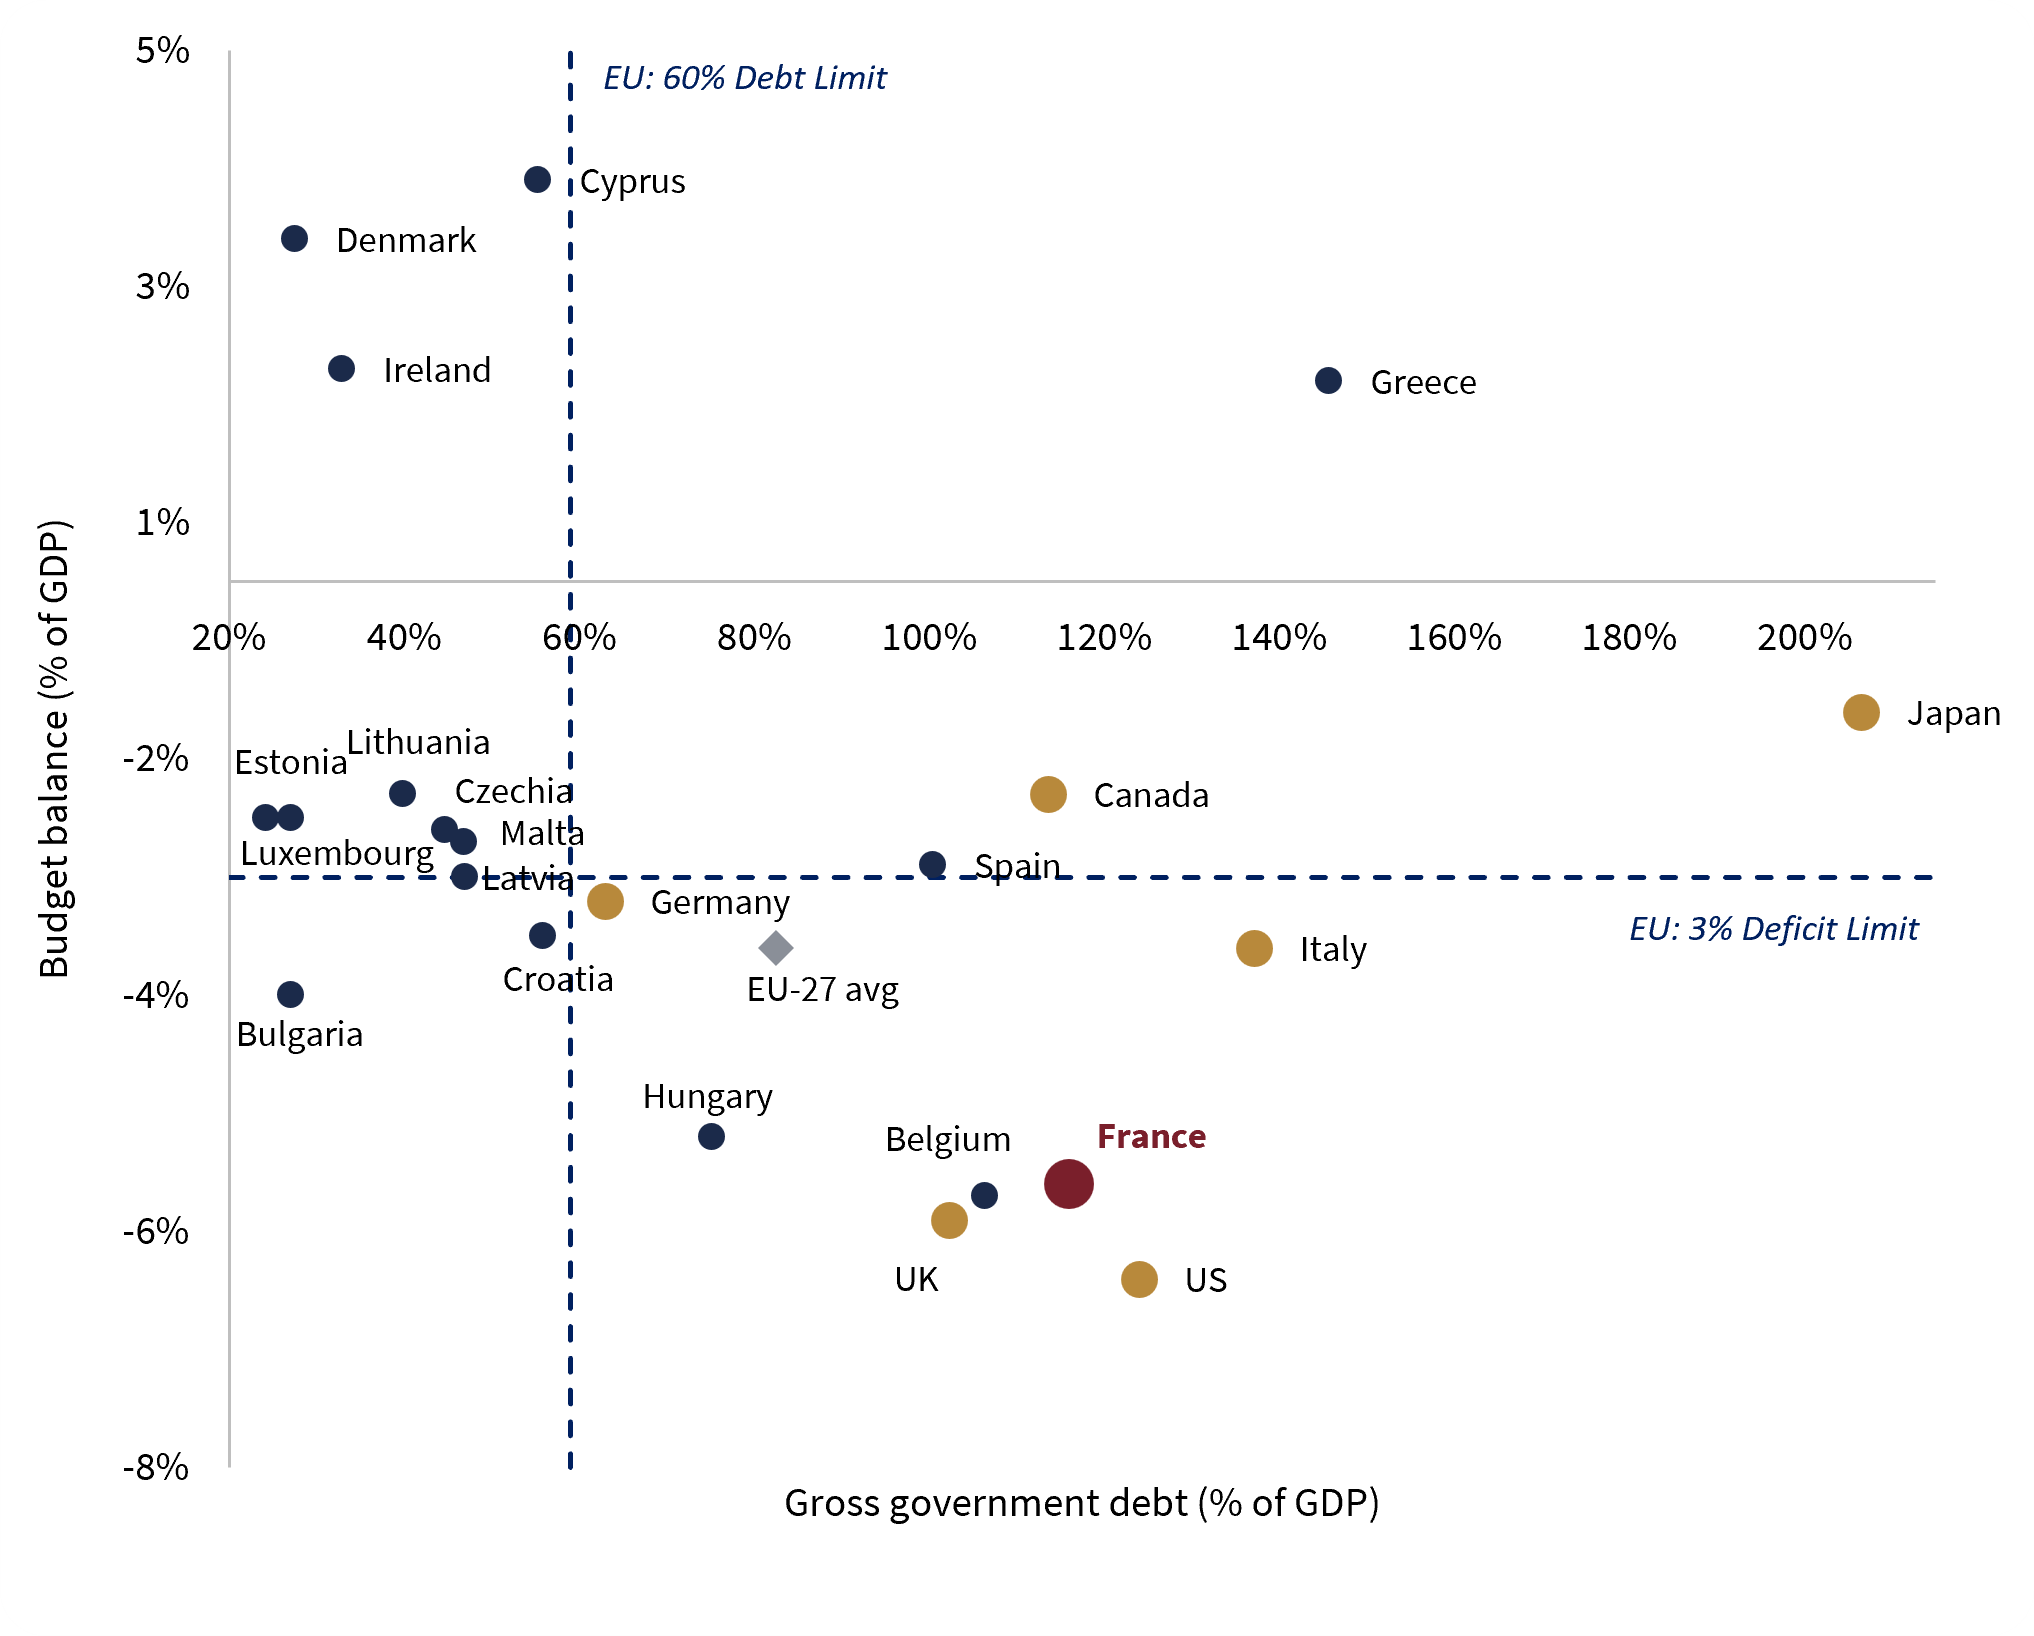
Source: Debt derived from IMF World Economic Outlook; Deficit derived from Eurostat (EU members) and from IMF WEO (US, Japan, UK, Canada).
Concerns about foreign investors selling OATs, weakening the euro, and pushing yields still higher should be kept in perspective. We should remember that France remains a large, rich, diversified economy with deep markets – and its credit is still firmly investment-grade, rather than distressed. French debt has an average life of about eight and a half years: higher market yields therefore feed into the interest bill gradually, as older, low-coupon bonds mature and are refinanced, rather than all at once.
There also remains an untested backdrop: the Transmission Protection Instrument. Since 2022, the European Central Bank has had an "anti-fragmentation" tool designed to buy a member state's bonds if its spreads widen in a way judged unwarranted by fundamentals. Ironically, this unused tool was intended to prevent a disorderly blow-out in peripheral spreads. However, with peripheral markets largely stable today – and borrowing costs below that of France – it could conceivably serve a very different purpose: stopping a self-fulfilling ‘run’ on French sovereign debt. Though its potential deployment for France would be in extremis – and likely subject to legal and political scrutiny.
But more prosaically, yields have been rising across the board, not just in France. Most of the time, as we often note here, the business cycle – not politics or budgets – is the main driver of bond yields, and economic activity and inflation have looked a little firmer across the developed world. Our inclination is to see the wider spread as a potential opportunity if (as we think) fiscal credibility remains intact and the political debate does not threaten France’s commitment to the EU or its debt obligations.
This looks to be a politically precarious moment, but not yet a sovereign-debt crisis. For the time being, though, France’s political and fiscal risk premium may not have peaked, and momentum argues against moving too early.
Ready to begin your journey with us?
Speak to a Client Adviser in the UK or Switzerland
Past performance is not a guide to future performance and nothing in this article constitutes advice. Although the information and data herein are obtained from sources believed to be reliable, no representation or warranty, expressed or implied, is or will be made and, save in the case of fraud, no responsibility or liability is or will be accepted by Rothschild & Co Wealth Management UK Limited as to or in relation to the fairness, accuracy or completeness of this document or the information forming the basis of this document or for any reliance placed on this document by any person whatsoever. In particular, no representation or warranty is given as to the achievement or reasonableness of any future projections, targets, estimates or forecasts contained in this document. Furthermore, all opinions and data used in this document are subject to change without prior notice.